How is the credit limit determined for Loan Against Mutual Fund?
16 January 2025 5 min read
How is the Credit Limit Determined for Loan Against Mutual Fund?
A Loan Against Mutual Fund (LAMF) is a convenient way for investors to access funds without having to sell their mutual fund investments. However, the key question that arises for potential borrowers is: How is the credit limit determined for a loan against mutual funds? The credit limit for a Loan Against Mutual Funds is primarily based on the market value of the mutual funds held by the borrower, with a loan-to-value (LTV) ratio set by the lender. Understanding how the credit limit is determined is crucial for borrowers to know how much they can borrow and what factors might influence the loan amount.
In this blog, we’ll explore how the credit limit is determined, the benefits of loans against mutual funds, the types of mutual funds eligible for such loans, and why Liquify is a great choice for this financial solution.
Benefits of Loan Against Mutual Fund
Loans against mutual funds offer numerous advantages, making them an attractive option for investors:
- Quick Access to Funds: You can avail of funds without selling your investments, ensuring that you don’t miss out on any potential growth in the mutual fund market.
- Lower Interest Rates: Since the loan is secured against your mutual fund units, the interest rates are usually lower compared to unsecured personal loans.
- Flexible Repayment Terms: Lenders typically offer flexible repayment options, allowing borrowers to pay back in easy installments.
- Maintain Investment Growth: The biggest advantage is that your mutual fund units remain intact, and any appreciation in their value benefits you, even while the loan is active.
Which Mutual Funds Are Eligible?
Not all mutual funds are eligible for a Loan Against Mutual Funds. Typically, the following types of funds are considered:
- Equity Mutual Funds: These are often eligible for LAMF since they tend to offer better returns and are a common choice among investors looking for capital appreciation.
- Debt Mutual Funds: These are also eligible, though they typically come with a lower loan-to-value ratio due to their more conservative nature.
- Hybrid Funds: These can also be used, but the loan amount will depend on the equity-to-debt ratio and the market value of the investments.
- Gold Funds and Other Specialized Funds: These can also be considered by some lenders, though they may have different eligibility criteria.
It’s important to note that the eligibility and loan terms may vary depending on the lender’s policies and the type of mutual fund involved.
Determining Loan Limits
The credit limit for a Loan Against Mutual Funds is determined based on the market value of the mutual fund holdings, and the loan-to-value (LTV) ratio applied by the lender. The LTV ratio refers to the percentage of the mutual fund value that can be borrowed.Here’s how the loan limit is typically calculated:
- Loan-to-Value Ratio (LTV): The LTV ratio is the percentage of the mutual fund’s market value that you can borrow. This usually ranges between 50% to 75%, depending on the type of mutual funds and the lender’s policies.
For example, if the mutual funds held by the borrower are worth ₹5,00,000 and the lender offers an LTV of 60%, the borrower can get a loan of ₹3,00,000. - Market Fluctuations: Since mutual funds are subject to market fluctuations, the loan amount may change as the value of the mutual fund holdings fluctuates. A drop in the market value could potentially trigger a margin call, requiring the borrower to deposit additional funds or collateral.
- Fund Type: The type of mutual fund also affects the loan limit. Equity funds typically offer a higher LTV ratio compared to debt or hybrid funds because they are expected to provide higher returns.
- Risk Assessment: Lenders may adjust the credit limit based on their risk assessment of the investor’s portfolio. If the mutual fund holdings are concentrated in high-risk investments, the loan limit may be lower.
Why Choose Liquify
Liquify is a leading platform for Loan Against Mutual Funds, offering a seamless and transparent process. Here’s why you should choose Liquify for your LAMF needs:
- Quick Disbursal: Liquify ensures quick processing and disbursal of loans, so you don’t have to wait long to access funds.
- Minimal Paperwork: The platform provides a digital application process with minimal documentation, making it easier for investors to apply.
- Competitive Rates: Liquify offers attractive interest rates and flexible loan terms that make borrowing more affordable.
- Transparency and Flexibility: With Liquify, borrowers have a clear understanding of the loan terms, and the platform offers flexible repayment options.
Conclusion
A Loan Against Mutual Funds offers an excellent solution for investors seeking liquidity without having to sell their mutual fund investments. The credit limit is primarily determined by the LTV ratio, which depends on factors like the type of mutual fund, its market value, and the lender’s policies.
Loans against mutual funds provide various benefits, such as quick access to funds, lower interest rates, and flexible repayment options. However, borrowers should also be mindful of the risks involved, including market fluctuations and the potential for margin calls.
Need cash without liquidating your investments?
Get a credit line from ₹25,000 at 9.75% p.a. Your mutual funds remain 100% invested.
More Insights from Liquify
View all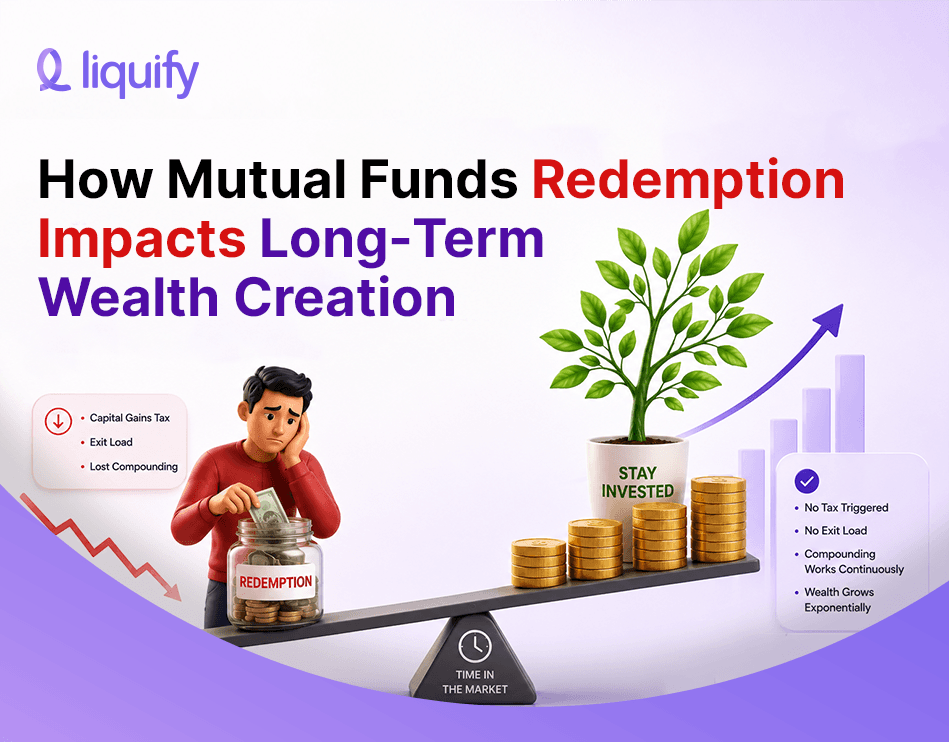
How Mutual Fund Redemption Impacts Long-Term Wealth Creation
How Mutual Fund Redemption Impacts Long-Term Wealth Creation Every month, a large number of Indian investors make a mutual fund re...
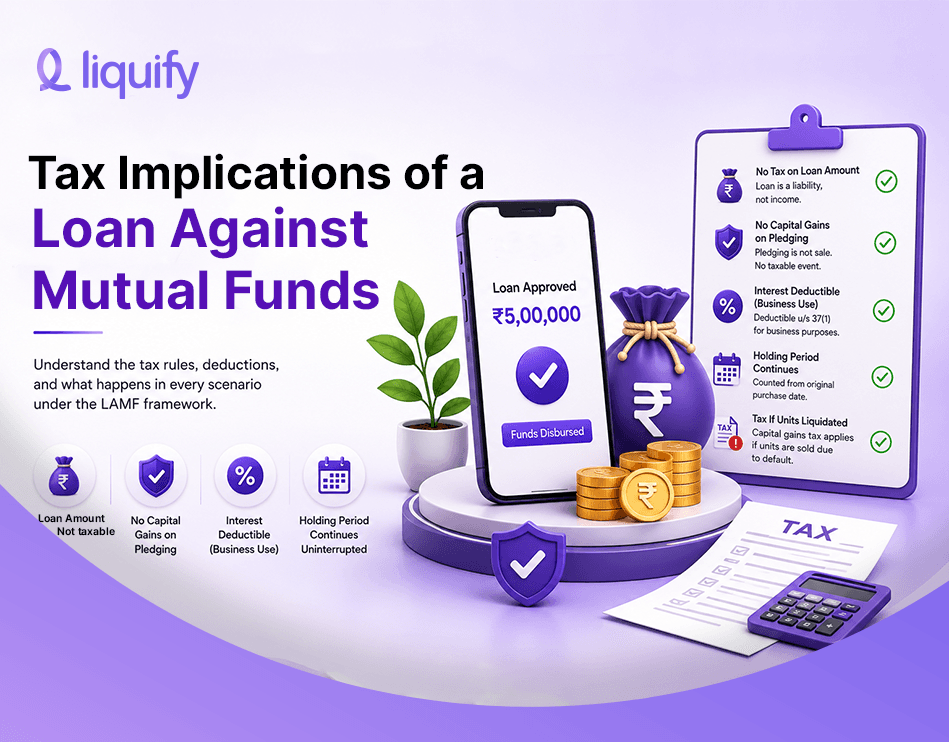
Loan Against Mutual Funds Tax 2026
Tax Implications of a Loan Against Mutual Funds The biggest tax advantage of a loan against mutual funds tax 2026 framework is si...
Emergency Fund vs Mutual Fund Loan
Emergency Fund vs Loan Against Mutual Funds Most financial advice treats emergency fund vs mutual fund loan as separate topics. Th...